

Dean Colling, Jonathan Vapsva
November 10, 2026
In The Midst of Market Volatility – We’re Staying the Course
History, earnings and valuations all point to a constructive year ahead
It has been a difficult stretch for markets. Since setting a record in early October, the S&P 500 has given back roughly 6%, and the technology-heavy Nasdaq has fallen more than 10% from its peak. Three worries have converged: questions about whether the pace of AI spending can be sustained, inflation that has proven stickier than hoped as higher oil prices keep the U.S. Federal Reserve on hold, and the uncertainty of the run-up to the U.S. midterm elections. On November 5, concerns about tighter rules on data-centre development after the election sent the S&P 500 down 4.4% in a single session, marking its worst day since the 2025 “Liberation Day” tariff shock.
Moves like these are unsettling, and we understand why. A couple of months ago, we sent a note titled “There’s Always a Reason to Sell.” The past five weeks have supplied several. But history, and our own experience over more than three decades, tells us this is exactly the kind of period when discipline is rewarded.
History Favours the Patient
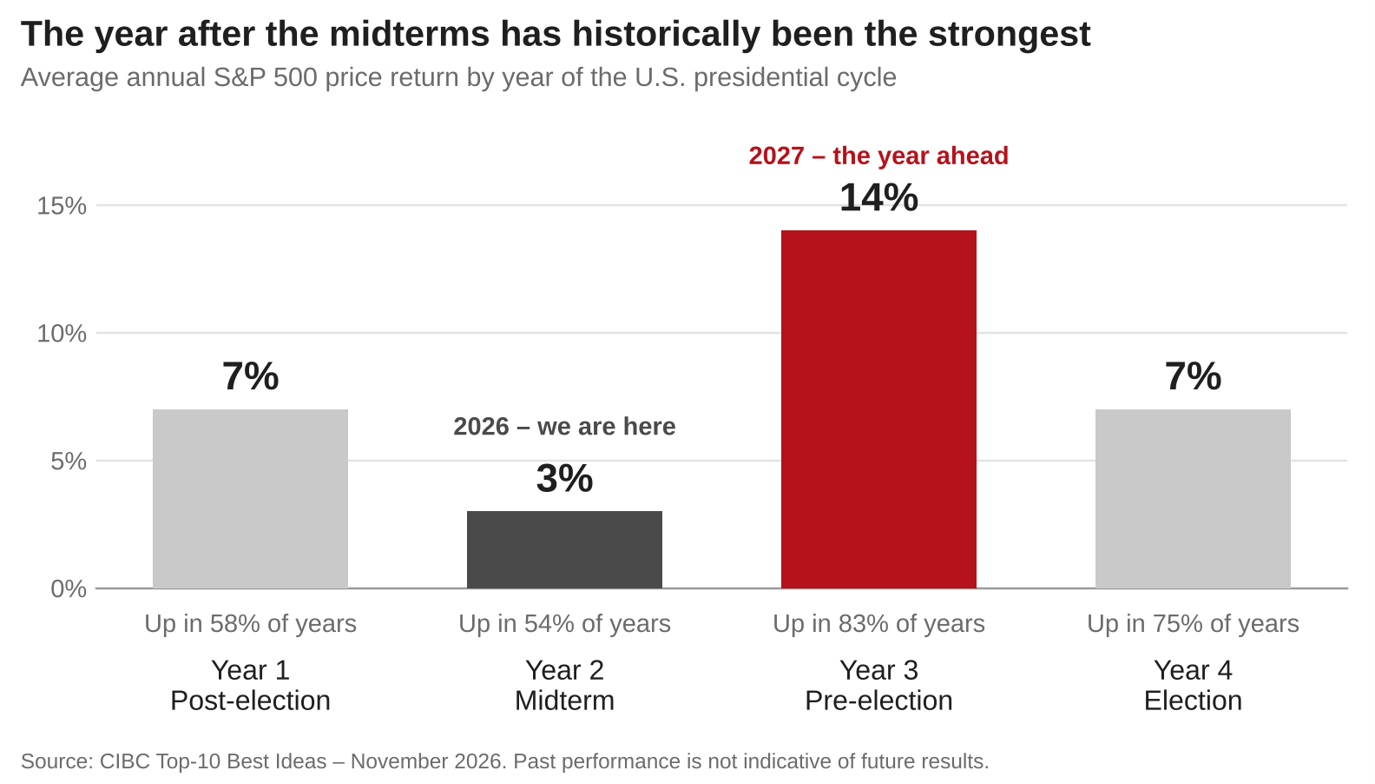
Investors crave certainty, and elections, by their nature, delay it. That shows up clearly when annual S&P 500 returns are grouped by year of the four-year U.S. presidential cycle. The second year, the midterm year we are in now, has historically been the weakest, averaging about 3%. The year that follows has been the strongest, averaging about 14% and finishing higher in more than four out of five years.
The months immediately after a midterm vote have also tended to be positive, as the table below shows. This November has
started on the wrong foot, a useful reminder that these are tendencies rather than guarantees, but the pattern of uncertainty giving way to steadier markets has been remarkably consistent.
S&P 500, midterm years since 1950 | November | December |
Average Return | +2.7% | +0.8% |
Median Return | +2.2% | +1.3% |
Finished the month higher | 79% of the time | 63% of the time |
Source: CIBC Top-10 Best Ideas – November 2026. Past performance is not indicative of future results.
Earnings Are Doing the Heavy Lifting
Beneath the volatility, corporate fundamentals remain strong. With nearly 90% of S&P 500 companies having reported,
third-quarter earnings are up about 31% from a year ago, marking the third straight quarter of growth above 25%, and all eleven sectors are growing. Importantly, growth is broadening: companies outside the “Magnificent 7” are now growing earnings faster than the AI megacaps. Analysts expect growth to moderate in 2027 but remain healthy, in the mid-teens.
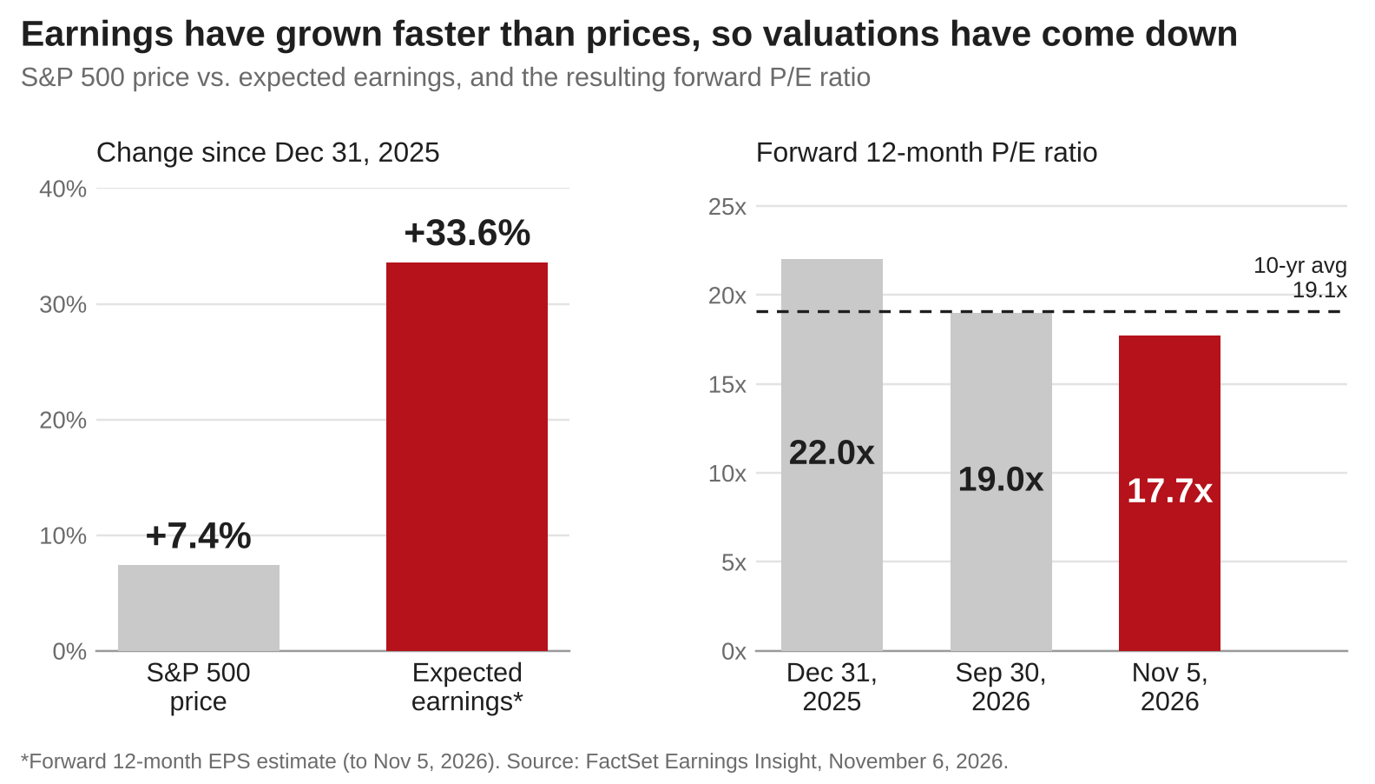
That combination has quietly made the market cheaper. Since the start of the year, the S&P 500’s price is up about 7%, while expected earnings over the next twelve months have risen by about a third. As a result, the forward price-to-earnings ratio has fallen from 22x to about 17.7x – below its five- and ten-year averages and the lowest level in three years. Valuations have come down not because prices collapsed, but because earnings grew into them.
What This Means for Your Portfolio
Stay invested. Pullbacks are the price of admission for long-term equity returns. Trying to step aside and time the re-entry has historically been costly, because the strongest days often arrive close to the weakest ones.
Keep watching the risks. Inflation and the path of interest rates, the durability of AI investment and any policy changes
affecting data centres, oil prices and geopolitics, and a sharper-than-expected slowdown in earnings all bear watching. We monitor them closely and will adjust if the facts change.
Use volatility, don't fear it. Where appropriate, we are using weakness to rebalance and to add to high-quality businesses at more attractive prices.
Lean on diversification. Recent weakness has been concentrated in AI-related names. Broad diversification across sectors, regions and asset classes – supported by earnings growth that is now broadening – helps manage risks no historical pattern can capture.
Rhyming But Not Repeating
Every year is different, so while we take note of these historical relationships, we don’t take direction. But when we put the
pieces together – a historically favourable point in the election cycle, earnings growth that remains robust and is broadening, and valuations that have reset to more reasonable levels – we remain constructive on the year ahead.
If you would like to talk through what this means for your portfolio, please reach out to any member of the team.

Sources: FactSet Earnings Insight, November 6, 2026; FactSet Earnings Season Update, November 6, 2026; CIBC Top-10 Best Ideas – November 2026; Associated Press.
Market data as of November 6, 2026.
Related posts
Dean Colling, Jonathan Vapsva
October 15, 2026
Why Fixed Income Deserves a Fresh Look
Fixed income has felt anything but dependable in recent years, challenged by rising rates, inflation shocks, and disappointing returns. This post explores why today’s higher yields and reset valuation...
Read moreDean Colling, Rachel Campbell-Johnson
September 17, 2026
Beyond the Headline: How AI Is Quietly Reshaping Work
AI is reshaping work, but not through the mass job losses many fear. Its impact is showing up more quietly through slower hiring and pressure on entry-level roles. This post looks at what the data is ...
Read more